Purpose

I will try my best to provide detailed info on various cars and what is like to live with them, I have already produced a few for Jaguar-car-forums, I will do my best to be unbiased, but it will be hard for some cars. I will re-produce press releases and copy from other motoring news.
Showing posts with label 208. Show all posts

Saturday, 24 September 2016

Sales within Europe have driven higher due to double digit gains in 16 of the 29 countries, with YTD sales passing 10 Million.

  • The growth can be attributed to double-digit increases in 16 of the 29 countries analysed
  • Year-to-date registrations surpassed the 10-million-unit mark, up by 7.7% compared to last year
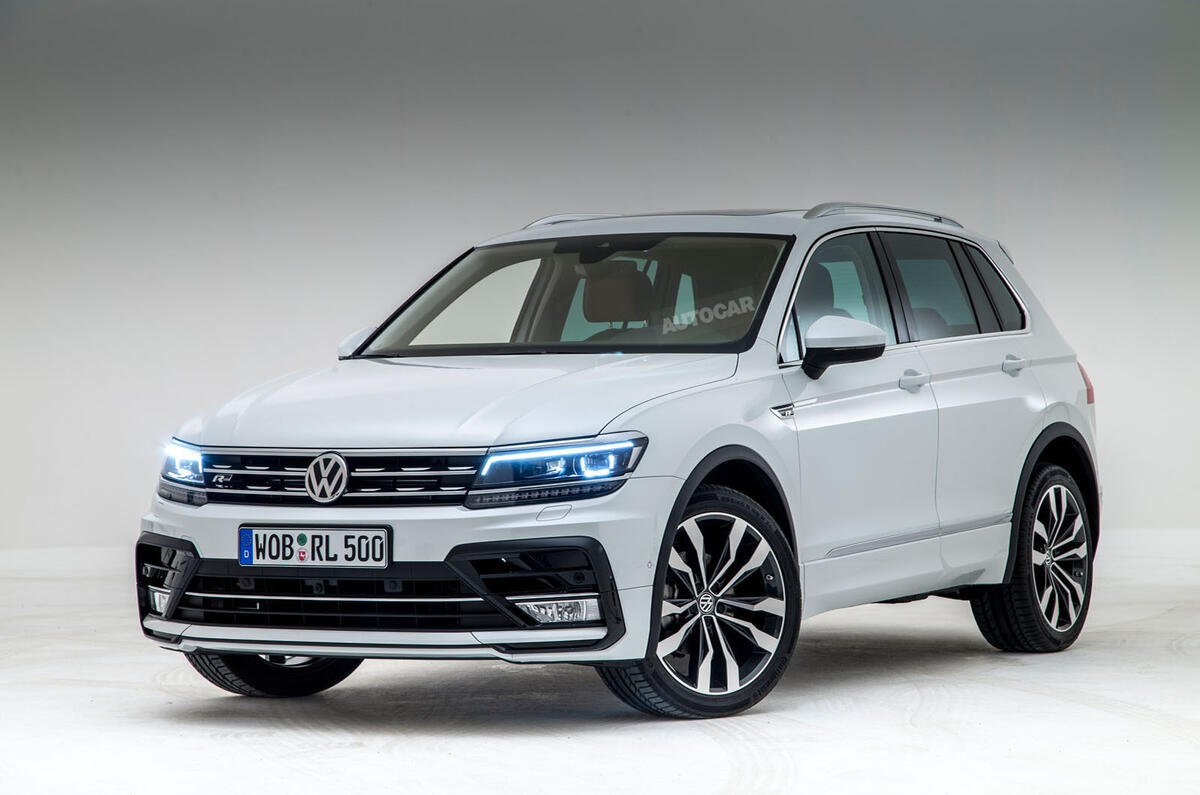
  • The Volkswagen Tiguan became Europe’s sixth best-selling model and the best-selling SUV with sales up more than 79%
New car registrations, in the 29 European markets analysed by JATO Dynamics, increased by 9.3% in August compared to the same month last year, with 855,300 units registered compared to 782,531 in 2015. For the year to date, registrations surpassed the 10 million unit mark, an increase of 7.7%, when compared to the same period in 2015.
This increase can be attributed to the double-digit growth posted in 16 markets, including Italy and Spain which recorded increases of 20% and 14% respectively. Germany posted a strong increase of 8%, while Belgium and Poland were up by more than 20% each. 
Smaller markets including Romania, Hungary and Croatia performed even better with increases for the month of 69%, 44% and 39% respectively. 
SUVs were the biggest contributor to the upturn seen in August, accounting for more than 25% of all registrations and achieving double-digit increases in 28 of the 29 markets analysed. Overall, volumes for the SUV segment increased by 30%. This can largely be attributed to the recently launched new models.
The biggest SUV segment volume growth was seen in Italy, which recorded a 53% increase on last year, followed by Ireland at 48%, Belgium at 43%, Portugal at 41% and Norway with 40%. 


In comparison to the growth of SUVs, traditional segments continued to lose ground, with the City-car and Large Sedan segments both posting declines of 0.7% and 10.9% respectively. Similarly, demand for the Sports segment cooled with the segment posting a small growth of 2% following months of dramatic increases.
All brands within the Volkswagen Group posted volume increases, with only Volkswagen, Audi and Skoda, growing less than the market average. Volkswagen Group retained its position as the best-selling manufacturer but its modest growth of 5.2% was not enough to prevent it losing market share. In a growing market, the car maker posted the biggest market share drop of any group, falling from 26.7% in August 2015 to 26.0% in August 2016. Compact cars accounted for the largest share of Volkswagen Group’s registrations, despite the Compact segment’s volume dropping by 5.4%. Volkswagen Group has made progress in the SUV segment, with its SUV range recording an increase of 24.8%.
The Renault-Nissan alliance continued on its upward trajectory, with the group displaying a volume increase of 13.1% which is more than the total market average. This was possible due to the outstanding performance of the Dacia brand, which posted a 44.3% increase compared to the same period last year. The alliance also continue to lead the European SUV segment, with one in every four SUVs sold being from the Renault, Dacia, Nissan or Infiniti brands. PSA lost 0.57 points of its market share and posted a small increase in registrations of 2.8%, placing it third in the ranking. The French manufacturer is attempting to boost its registrations with the upcoming launches of the 3008 Compact and the 5008 Midsize SUV.
Meanwhile, Hyundai-Kia Group posted a significant growth of 15.9%, largely due to its small car category and the outstanding performance of its SUVs, with the Hyundai Tuscon posting the highest market share increase of all models. Daimler Group completed the top five group ranking, with a dramatic increase of 18.2%, the second highest amongst the top ten, just behind FCA with 19.9%. The only car makers to see declines in registrations were Volvo, Mitsubishi and Subaru, posting drops of 14.8%, 9.8% and 6.8% respectively.
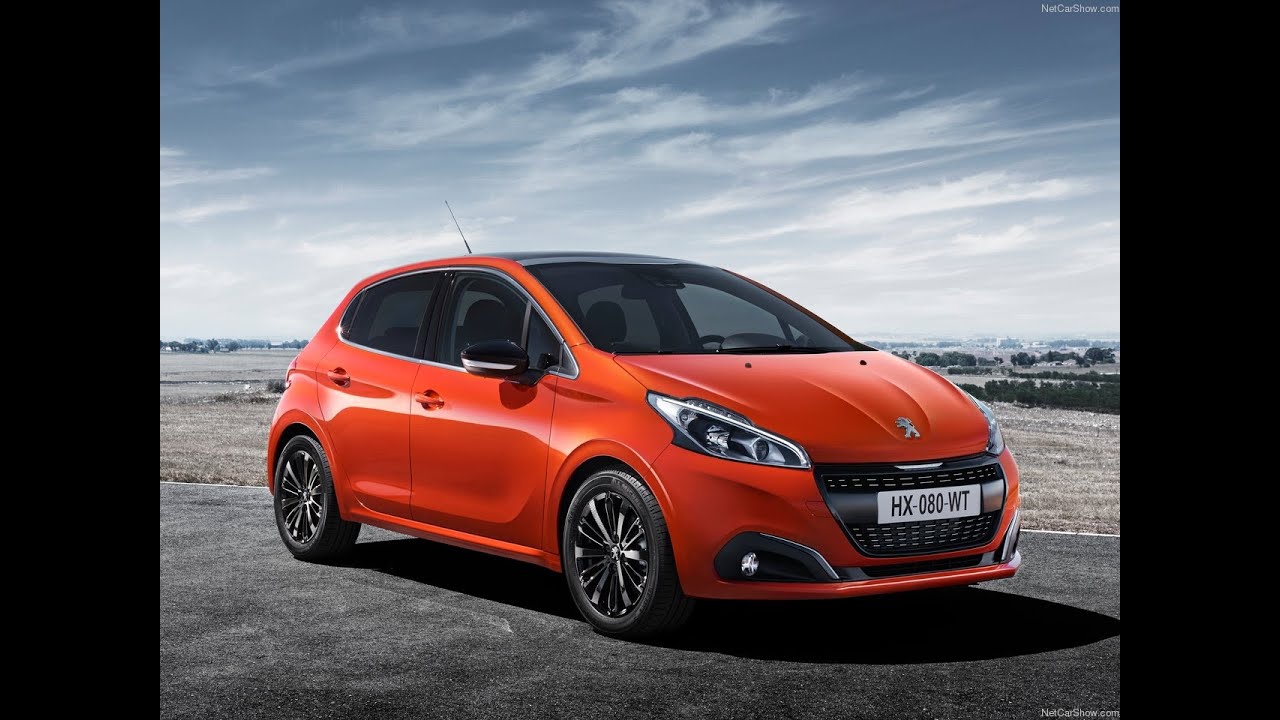
The Volkswagen Golf maintained its position as Europe’s best-selling model in August, with 29,500 units registered, which represented an 11.5% decline on the same period last year. The model maintained its lead despite posting the highest market share drop of any model, moving from 4.3% in August 2015 to 3.5% in August 2016. In contrast, its rival the Opel/Vauxhall Astra was the fourth best-selling model with 14,400 vehicles registered in August 2016, a 23.0% increase on the same period last year. Second in the ranking was the Volkswagen Polo, despite a 10.6% decline; Polo registered just 14,751 units compared to 16,504 for the same period last year. Nonetheless, the Polo was still ahead of the Ford Fiesta even with the model’s significant 11.3% increase in registrations. Amongst the other subcompacts, the Peugeot 208 posted a dramatic 16.5% increase which saw it outperform its rivals the Opel/Vauxhall Corsa and Renault Clio.
In the SUV segment, the Volkswagen Tiguan stood out, registering 14,300 units which is a significant increase of 79.1% which made it the sixth best-selling model in Europe and the best-selling SUV.  The Renault Captur similarly performed well, posting a 19.5% increase which saw it outperform the Nissan Qashqai.
The Audi A4 was the best-selling vehicle in the mid-size range, it entered the top ten ranking with an increase of 44.5% and 12,200 units registered in August 2016.  Other significant segment winners were the Mini Clubman, Honda HR-V, Mercedes GLC, BMW X1, Volkswagen Touran, Hyundai Tuscon, Toyota Prius, Citroen C-Elysee, Ford Ecosport and the Toytoa RAV4.
Felipe Munoz, Global Automotive Analyst at JATO Dynamics commented: “Following the slightly disappointing results in July, August has seen a return to growth. With the Paris Motor Show at the beginning of October, we would expect new launches to further impact the market in Q4 2016.”

Friday, 16 September 2016

European car sales grew by a healthy 9.3% in August led by Italy, Spain and Germany.

  • Italy saw its best August results since 2009, increasing car registrations by 20.2%
  • Spain’s market was boosted by an outstanding growth on rental car registrations, which were up 48%
  • Year-to-date registrations were up 7.6%, with 7.33 million units registered overall so far this year
Registrations in Europe’s ‘Big 5’ markets saw a healthy increase of 9.3% in August, as market conditions improved following the 2% decline seen in July. Overall, registrations for August totalled 562,046 units, up from 514,428 in August 2015. 
Registrations YTD totalled 7.33 million units which is a 7.6% increase on the same period in 2015, SAAR figures came in at 10.92 million units.
While all five markets posted positive growth, Italy was the leader, posting its best August results since 2009 with a 20.2% increase on the same month last year, going from 60,065 units in August 2015 to 72,179 units in the same period this year, in part due to an additional working day.  

The Spanish market grew by 14.3% compared to the same period last year, largely due to record tourist numbers resulting in a 48% increase in rental car registrations. Europe’s largest market, Germany, posted an 8.3% increase, compared to the same period last year. 
This was driven by growth in private registrations which were up 19% on last year due to positive economic development, a healthy level of employment, and two additional working days in August. Both France and the UK posted a modest growth of 6.6% and 3.3% respectively.
Volkswagen Group remained Europe’s largest car maker, posting a 5.8% increase on last year, having registered 143,324 units in August 2016 compared to 135,483 units in August 2015. 
However overall, the German group lost market share, recording the biggest market share drop of all the car makers analysed, going from 26.3% in August 2015 to 25.5% in 2016 as double digit growth in Germany was offset by falls in the UK and France. 
In contrast, Renault-Nissan alliance registrations grew by 12.2%, taking its overall market share to 12.7%, compared to 12.4% last year. 
The group saw strong growth of 27.3% and 32.7% in Italy and the UK respectively, which was particularly boosted by a 33.6% increase posted by Dacia, which outsold Nissan in the ranking. PSA and Ford both lost market share, whilst Opel/Vauxhall dropped by 1% and fell one position in the brand ranking.
The big winner of the month was Daimler, with Mercedes posting double-digit gains in all of the five markets and becoming the third best-selling brand of the month. 
FCA increased its market share by 0.78 percentage points due to the double-digit growth of its Fiat, Jeep, Alfa Romeo and Abarth brands, a 173% increase in sales at Maserati. Hyundai-Kia grew by 21.7%.
“As the market continues to shift and Volkswagen brands continues to slowdown, other brands continue to improve in the mainstream market, such as Dacia, Fiat and Hyundai-Kia which have all seen strong growth, whilst in the premium market, Mercedes is continuing to perform well,” said Felipe Munoz, Global Automotive Analyst at JATO Dynamics.
SUVs continued to boom, accounting for 25.9% of the total market, which is a dramatic increase considering the segment barely outsold subcompact (B-Segment) vehicles in August 2015. 
The SUV segment’s outstanding growth can largely be attributed to midsize and compact SUVs which posted increases of 55.1% and 36.1% respectively. Particularly noteworthy is the new Volkswagen Tiguan, which posted a 74% increase and was the best-selling SUV across the five markets and the fifth best-selling model overall. 
The Tiguan outsold the popular Nissan Qashqai which posted a 2.1% decline, and was significantly ahead of the fast-growing Kia Sportage (+41.3%), Hyundai Tucson (+326.4%) and Renault Kadjar (+79.9%). 
In the B-SUV segment the Opel/Vauxhall Mokka maintained its lead, despite recording a 0% growth, but was closely followed by the Renault Captur which recorded a 9.8% increase compared to the same period last year. 
Other big winners in the segment included the Peugeot 2008, Ford Kuga and Dacia Dusta which posted increases of 40.3%, 52.9% and 34.6% respectively.
The Subcompact segment (B-Segment) was boosted by the Dacia Sandero which increased registrations by 46.4% compared to the same period last year, and was the seventh best-selling model across the five markets in August 2016. 
The Peugeot 208 outsold its popular rivals Renault Clio (down 14.3%) and Volkswagen Polo (down 15.5%) to become the second best-selling subcompact.
The model ranking was again led by the the Volkswagen Golf which remained the best-selling car across the five markets, selling 20,722 units, posting a 5% decline when compared to the same period last year. 
Despite posting a 7.5% increase in Germany, double digit drops across the other markets hindered the model’s performance. 
Despite this, the Golf’s volume was more than double that of the Opel/Vauxhall Astra, which was second in the C-Segment ranking posting a decline of 7.7%. The segment’s big market share winners were the Fiat Tipo, Mini Clubman and Seat Leon.
“While the latest Volkswagen models have helped the brand offset drops posted by their traditional products, other brands gained market share by taking advantage of the booming SUV segment,” concluded Munoz.

Monday, 29 August 2016

UK RECALL #8 - Over time fuel may leak on certain 2014 Peugeot 208, 308 and 2008 models.

Vehicle Details

Reference :R/2016/160
Manufacturer Ref :HJC 
Make:PEUGEOT
Model :208, 2008 and 308
Launch Date :14/07/2016
Numbers Involved :86
Build Start Date :15/01/2014
Build End Date :12/06/2014 

Recall Details

Concern :FUEL MAY LEAK
Description :The fuel injectors supply rail could develop a leak over a period of time leading to a drop in fuel pressure which can affect the operation of the stop start system. In some extreme cases the engine might not restart and a spray of petrol under the bonnet may occur which is a fire risk.
Remedial Action :Recall the vehicles that are likely to be affected and check the fuel injector supply rail. Where necessary replace the fuel injector supply rail.
Vehicle Id :VF3******ES138371 to VF3******ES137145
VF3******ES138371 to VF3******ES137145

Other Vehicles Affected (Click the vehicle to perform an extended search)

  • PEUGEOT - 308
  • PEUGEOT - 208
  • PEUGEOT - 2008

Friday, 26 August 2016

European car sales dropped by 2,3% in July, but still is well ahead on the full year to date.

  • New car registrations dropped by 2.3% in July compared to the same period last year
  • Volkswagen continued to be the best-selling brand despite a reduction in overall market share
  • The SUV segment continued to grow, posting an 11.9% increase
New car registrations in the 29 markets analysed by JATO Dynamics dropped by 2.3% in July, falling from 1.18 million in July 2015 to 1.16 million for the same period this year. This fall in registrations marked the end of 34 months of continuous growth, the last time European registrations fell was August 2013. 
The two fewer working days in July may have been a contributor to this result, along with the significant decline of two of the largest European car groups, PSA and VW, who recorded a 13.2% and 8.8% fall in registrations respectively.
The UK posted a slight increase of 0.1% which is an improvement on June’s figures. Of the large markets, France and Germany recorded significant drops of 9.6% and 3.9% respectively, whilst the others recorded modest increases, with Italy posting a 2.6% rise and Spain a 4.4% increase.

Volkswagen was the best-selling brand, with 136,393 units registered, accounting for 11.8% of the total market. But in comparison, in July 2015 its volume of 152,863 accounted for 12.9% of the total market. 
Despite still leading the market in terms of sales, Volkswagen recorded the highest drop of any brand in the top ten, falling by 10.8% compared to the same period last year, closely followed by Skoda and Peugeot who both recorded a 10.5% drop. 
Volkswagen’s fall in demand could be attributed to the emissions issue and anticipation ahead of the launch of the updated version of the Volkswagen Golf at the Paris Motor Show in October.


Mercedes posted the highest increase in the top ten, but this was a modest 3.7%, which saw the brand register 66,153 units in July 2016. Outside of the top ten, Dacia (+11.5%), Suzuki (+19.5%), Mini (+10.7%), Land Rover (+33%), Honda (+15.3%) and Jeep (+11.4%) recorded double-digit growth largely driven by their SUVs. 
Other strong performers were Infiniti which posted a dramatic increase of 218% registering 1,768 units, largely due to the popularity of the Q30 and QX30. Jaguar was another big improver, posting a 32.5% increase due to strong demand for its mid-size SUV the F-Pace.
The Volkswagen Golf was still the best-selling model, with 36,540 units registered in July, but its volume dropped considerably, resulting in the model’s second lowest market share since December 2012. 
By comparison, in July 2015 Volkswagen registered 46,628 models. This decline coincides with the model’s biggest rival, the new generation Opel/Vauxhall Astra becoming the fourth best-selling car in Europe, registering 20,954 units, up by 26% on the same period last year. 
The other big players all posted double digit falls, including the Ford Focus (-12.3%), Skoda Octavia (-17.9%), Peugeot 308 (-19.7%) and the Audi A3 (-25.9%). The Mercedes A-Class and the Volvo V40 were two of the C-segment models that saw an increase in sales.
In the subcompact segment it was the Opel/Vauxhall Corsa which stood out, registering a significant increase of 9.2% in contrast to its major rivals such as the Volkswagen Polo, Ford Fiesta and Renault Clio which posted declines of 6.1%, 3.3% and 11.4% respectively. 
The Dacia Sandero was the other popular subcompact to post an increase with a dramatic 30.5% rise on the same period last year.
Felipe Munoz, Global Automotive Analyst at JATO Dynamics commented: “July marked the first decline in new car registrations in almost three years. This was largely driven by market conditions but there have been some significant drops recorded by some of the most popular models and brands.”
The SUV segment continued to grow, increasing registrations by 11.9% compared to July 2015, meaning it now accounts for 25.5% of the overall market, largely due to growth amongst the D-SUV and C-SUV groups, at the expense of the Compact, MPV and large Sedan/SW segments. 
The Nissan Qashqai kept its position as the best-selling SUV, registering 18,373 units, but this was a 6.9% drop on the same period last year. 
It was its newer rivals such as the Renault Kadjar, Hyundai Tucson and Kia Sportage which drove the segment’s growth, posting significant increases of 127%, 586% and 24% respectively. The new generation of the Volkswagen Tiguan meant the model reversed the downward trend seen last month, posting a small 0.2% increase.
The Peugeot 2008 boosted the B-SUV segment’s registrations with a rise of 6.9%. Amongst the larger SUVs, the Volvo XC60 maintained its lead of the mid-size group despite the rise of the Mercedes GLC, beating both the Audi Q5 and BMW X3. 
The Jaguar F-Pace was the eighth best-selling D-SUV. Volvo also led in the large SUV segment, thanks to the 15% increase posted by the XC90 which surpassed the BMW X5 (-4.8%), Mercedes GLE (+78%), Audi Q7 (+5.3%) and Range Rover Sport (+31%).
MPVs continued to decline, with registrations down by 11% despite the strong performance of the Volkswagen Touran which posted the highest percentage increase of the month (+144%). Other big segment winners were the midsize Audi A4 and Skoda Superb, the compact SUV BMW X1, the B-SUVs Ford Ecosport, Suzuki Vitara and Jeep Renegade, and the midsize SUV Nissan X-Trail. 
At the other end of the spectrum, the biggest drops were recorded by the Mercedes CLS, Porsche Panamera and Cayenne, Volkswagen Touareg, Citroen C5, DS 5, Nissan Pulsar, Hyundai i40 and Mitsubishi Space Star.
Felipe Munoz, Global Automotive Analyst at JATO Dynamics concluded: “Despite July’s slightly disappointing results, the full year figures are unlikely to be impacted too severely. The lower growth rates we are currently seeing are likely to moderate the larger growth rates we have seen in some of the biggest markets over the past three years”. 

Sunday, 14 August 2016

JATO's latest results shows that July was a poor month for the big five European countries, but YTD is still doing well.

  • France recorded the biggest fall, with new car registrations in July down 9.6% compared to the same period last year
  • New SUV sales grew by 12.5% and accounted for more than a quarter of all registrations, with traditional segments continuing to lose ground
  • Volkswagen lost more ground to its competitors as registrations fell 13.9% compared to July 2015
New car registrations in Europe’s ‘Big 5’ markets dropped by 2% in July, as market conditions halted the positive trend that had dominated over the previous 15 months. While Spain, Italy and the UK all posted modest growth in July, this could not fully compensate for the declines seen in France and Germany. 

Overall registrations for the month totalled 836,431 units, down from 853,701 units in July 2015. This slowdown is partly due to July 2016 having two fewer working days compared to July 2015. As Europe’s largest carmaker, the double-digit fall in VW Group’s monthly sales also had an impact.
The biggest decline was posted by France, with total registrations for July falling 9.6% compared to the same month last year, to 132,893 units. Sales in Germany, Europe’s largest market, fell 3.9%, taking its total registrations down to 278,878 compared to 290,196 last year. Spain grew 4.4% to 108,769 units and sales in Italy were up 2.6% to 137,368 units. Demand appeared to be cooling in the UK, which saw an increase of just 0.1% - this is as a result of exceptionally strong demand in 2015, and a continuing drop in private sales.

Volkswagen continues to be Europe’s largest brand, despite suffering the biggest market share drop of any of its competitors – 13.2% in July 2015 to 11.6% in July 2016. 
The decline shows that Volkswagen’s emissions issue continues to affect the company, with the car maker still being fined in some European markets. 
The biggest market share growth among the top 10 brands was posted by Fiat, this comes despite a fall in sales from the Fiat 500. Fiat’s sales were boosted by the new Fiat Tipo, and the continued growth of the B-SUV Fiat 500X. 
There was a good performance from the new Opel/Vauxhall Astra as the model continued to grab more market share in the compact segment, meaning that the Opel/Vauxhall brand was able to increase market share. 
Other big winners include Dacia, who posted double-digit growth in four of the five markets, thanks mostly to the Sandero hatchback, Kia’s new Sportage, and the good results of Land Rover’s updated Evoque. 
Infiniti posted the highest percentage increase (+233%) and was followed by Rolls-Royce, Bentley, Land Rover and Jaguar.
“Traditionally there is a drop in demand ahead of summer, but it is clear that Europe has started to feel the effect of Volkswagen’s emissions issue.” said Felipe Munoz, Global Automotive Analyst at JATO Dynamics.
In terms of segments, SUVs continued to grow their market share, with their registrations in July accounting for more than a quarter of the total market (25.8%). 
This growth is expected to continue as new important players such as the updated Ford Kuga, new Mini Countryman and Dacia Duster are unveiled over the upcoming months. 
The drop in traditional segments outweighed the growth of SUVs, with large/luxury cars, city-cars and MPVs posting the biggest losses of the month.
The Volkswagen Golf continued to lead as Europe’s favourite model, but its dominance is more vulnerable than ever. Its volume continued to decline as it awaits its first facelift, which is expected at the Paris Motor Show in October. 
New model releases have had a huge impact on Golf sales; in fact, while the current Golf (launched in 2011) posted a 24% fall, the new Opel/Vauxhall Astra grew by 17%. The Fiat Tipo was the best- selling compact car in Italy, and became the 12th best-selling compact car overall with 5,300 units. 
Among the top sellers, the biggest winner of the month was the Dacia Sandero which posted double-digit growth in four out of the five markets, and came in at 11th position with a volume growth of 27%. 
The Nissan Qashqai regained its place as the best-selling SUV in the big 5 European markets, after spending months behind the Renault Captur. In fact, the Captur was even outsold by the Opel/Vauxhall Mokka and the new VW Tiguan.
“Despite the slowdown in the market, the demand for SUVs is increasing, and is expected to keep growing, especially with new models being unveiled in the upcoming months,” concluded Munoz.

Wednesday, 10 August 2016

Peugeot has extended it's seriously popular Just Add Fuel® with Telematics onto the 308 and 308 SW models.

  • Popular Just Add Fuel® with Telematics now extended to PEUGEOT 308* and 308 SW*
  • £1,850 customer saving on the 308 and 308 SW in August and September**
  • Customers choosing the innovative Just Add Fuel® or PEUGEOT Passport are eligible for a further £1,350 in deposit contributions
In time for the ‘66-plate’ September market, PEUGEOT announces that the popular Just Add Fuel® with Telematics is now extended to the PEUGEOT 308 and 308 SW models (*exclusions apply).  
Launched 12 months ago, initially on the 108 range and later on 208 and 2008 SUV, Just Add Fuel® with Telematics has proved extremely attractive to retail consumers and is aimed primarily at customers aged from just 18 years, customers who do not have two-years no claim discount or those customers with children who have a requirement to drive the family car.

To further enhance this launch, PEUGEOT is also offering customers who purchase a 308 or 308 SW during this period a £1,850 customer saving (exc. 308 Access model).  
A customer placing a deposit of £1,500 on a PEUGEOT 308 PureTech 110 on Just Add Fuel® with Telematics will also receive an additional £1,350 in deposit contributions and see payments from £419 per month on an Active model and £426 per month on the Allure model. (Based on an 18 year old living in a low risk Band 2 Postcode)
Just Add Fuel® is PEUGEOT’s fixed price motoring package has hassle free benefits of a low single fixed monthly payment uniquely covering all motoring costs for the next three years.
  • No need to budget separately for insurance, servicing, road fund licence (where applicable), and roadside   assistance costs – as they are all included
  • No need to search for cheaper insurance each year – it stays the same over the three- year term
  • Fixed price motoring for three years means complete peace-of-mind
  • A completely transparent motoring package with no hidden costs
  • The opportunity to drive a new car every three years, so there’s no MOT or other costs
For customers not requiring the Telematics package, a PEUGEOT 308 PureTech 130 on Just Add Fuel® with a £1,500 deposit will see monthly payments of £296 for an Active model and £310 for an Allure. (Based on a 40 year old living in a low risk Band 2 postcode)
Customers choosing to finance with PEUGEOT Passport also benefit from the customer saving and deposit contributions.  With a competitive 4.9% APR PEUGEOT Passport rate available during the period, customers who place a deposit of £1,500 on a PEUGEOT 308 PureTech 130 Active model will see prices start from £268 per month and £281 per month on an Allure model.
* Models excluded – GT Line Blue HDi 150, GT and GTi by Peugeot Sport 250THP & 270THP
** Not available on Access

The extensive 308 range made simple:
SIX TRIM LEVELS: Access, Active, Allure, GT Line, GT and GTi by Peugeot Sport
PRICE RANGE: from £15,930 - £28.890 on the road MRRP
ENGINE CHOICE: seven petrol engines and transmission combinations (Four PureTech 82hp, 110hp S&S, 130hp S&S, 130hp EAT6 S&S and three THP 205hp S&S, 250hp S&S and 270hp S&S) Six BlueHDi diesel engines and transmission combinations (100hp S&S, 120hp S&S, 120hp EAT6 S&S, 150hp S&S, 150hp EAT6 S&S, 180hp EAT6 S&S)
TRANSMISSION: manual 5-speed and 6-speed and EAT6 automatic available
POPULAR MODELS: Allure (39%) | Diesel 1.6L BlueHDi 120hp S&S (41%) | Petrol 1.2L PureTech 130hp S&S (10%) and Petrol 1.2L PureTech 130hp S&S EAT6 (10%)
INTERESTING: GT Line (24%) | Diesel (74%) | Pearlescent White (5%) makes white 15% of range
COLOURFUL CHOICE: eleven colours available; two solid, six metallic, a pearlescent, a 3-layer ‘varnish’ paint finish and the Brand exclusive Coupe Franche (270THP only)
MOST POPULAR COLOUR: Nera Black (20%) White (15%) Aluminium (13%) and Twilight Blue (13%)