Purpose

I will try my best to provide detailed info on various cars and what is like to live with them, I have already produced a few for Jaguar-car-forums, I will do my best to be unbiased, but it will be hard for some cars. I will re-produce press releases and copy from other motoring news.
Showing posts with label july. Show all posts

Wednesday, 21 June 2017

The world readies for the launch of another All-New Jaguar, the E-Pace is coming !!!

  • Jaguar E-PACE combines sports car design and agility with everyday SUV practicality
  • Joins World Car of the Year-winning F-PACE and Jaguar’s all-electric I-PACE Concept SUVs
  • World Premiere of Jaguar E-PACE 13 July 2017
  • Indicative pricing from £28,500 in the UK
  • Visit jaguar.co.uk to sign up for further information in the lead-up to the reveal 


Jaguar introduces its new compact performance SUV, the Jaguar E-PACE. 

Joining Jaguar’s PACE family of performance SUVs, the E-PACE follows on from the successful F-PACE, which helped boost Jaguar’s sales by 83 per cent last year, and the all-electric I-PACE Concept which will go into production in 2018. 
Ian Callum, Director of Design, Jaguar, said: “The combination of sports car looks with Jaguar performance will ensure that the E-PACE stands out. 

Every Jaguar is designed to excite the senses, and we think E-PACE will do just that, albeit with its own individual character.” 

The Jaguar E-PACE features sports car-derived AWD technology and an all-Ingenium line-up of petrol and diesel engines, as well as a suite of connected technology and safety features. 
The compact performance SUV will be revealed to the world on 13 July. 

Saturday, 24 September 2016

Sales within Europe have driven higher due to double digit gains in 16 of the 29 countries, with YTD sales passing 10 Million.

  • The growth can be attributed to double-digit increases in 16 of the 29 countries analysed
  • Year-to-date registrations surpassed the 10-million-unit mark, up by 7.7% compared to last year
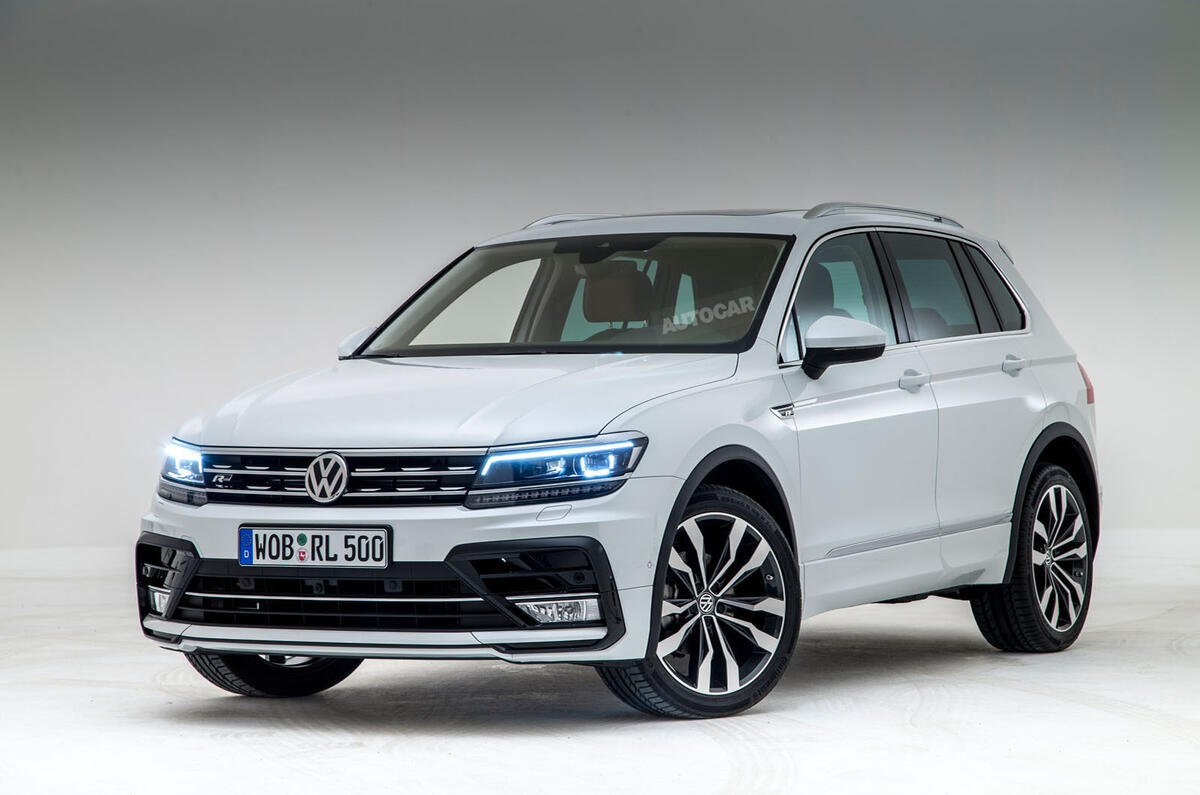
  • The Volkswagen Tiguan became Europe’s sixth best-selling model and the best-selling SUV with sales up more than 79%
New car registrations, in the 29 European markets analysed by JATO Dynamics, increased by 9.3% in August compared to the same month last year, with 855,300 units registered compared to 782,531 in 2015. For the year to date, registrations surpassed the 10 million unit mark, an increase of 7.7%, when compared to the same period in 2015.
This increase can be attributed to the double-digit growth posted in 16 markets, including Italy and Spain which recorded increases of 20% and 14% respectively. Germany posted a strong increase of 8%, while Belgium and Poland were up by more than 20% each. 
Smaller markets including Romania, Hungary and Croatia performed even better with increases for the month of 69%, 44% and 39% respectively. 
SUVs were the biggest contributor to the upturn seen in August, accounting for more than 25% of all registrations and achieving double-digit increases in 28 of the 29 markets analysed. Overall, volumes for the SUV segment increased by 30%. This can largely be attributed to the recently launched new models.
The biggest SUV segment volume growth was seen in Italy, which recorded a 53% increase on last year, followed by Ireland at 48%, Belgium at 43%, Portugal at 41% and Norway with 40%. 


In comparison to the growth of SUVs, traditional segments continued to lose ground, with the City-car and Large Sedan segments both posting declines of 0.7% and 10.9% respectively. Similarly, demand for the Sports segment cooled with the segment posting a small growth of 2% following months of dramatic increases.
All brands within the Volkswagen Group posted volume increases, with only Volkswagen, Audi and Skoda, growing less than the market average. Volkswagen Group retained its position as the best-selling manufacturer but its modest growth of 5.2% was not enough to prevent it losing market share. In a growing market, the car maker posted the biggest market share drop of any group, falling from 26.7% in August 2015 to 26.0% in August 2016. Compact cars accounted for the largest share of Volkswagen Group’s registrations, despite the Compact segment’s volume dropping by 5.4%. Volkswagen Group has made progress in the SUV segment, with its SUV range recording an increase of 24.8%.
The Renault-Nissan alliance continued on its upward trajectory, with the group displaying a volume increase of 13.1% which is more than the total market average. This was possible due to the outstanding performance of the Dacia brand, which posted a 44.3% increase compared to the same period last year. The alliance also continue to lead the European SUV segment, with one in every four SUVs sold being from the Renault, Dacia, Nissan or Infiniti brands. PSA lost 0.57 points of its market share and posted a small increase in registrations of 2.8%, placing it third in the ranking. The French manufacturer is attempting to boost its registrations with the upcoming launches of the 3008 Compact and the 5008 Midsize SUV.
Meanwhile, Hyundai-Kia Group posted a significant growth of 15.9%, largely due to its small car category and the outstanding performance of its SUVs, with the Hyundai Tuscon posting the highest market share increase of all models. Daimler Group completed the top five group ranking, with a dramatic increase of 18.2%, the second highest amongst the top ten, just behind FCA with 19.9%. The only car makers to see declines in registrations were Volvo, Mitsubishi and Subaru, posting drops of 14.8%, 9.8% and 6.8% respectively.
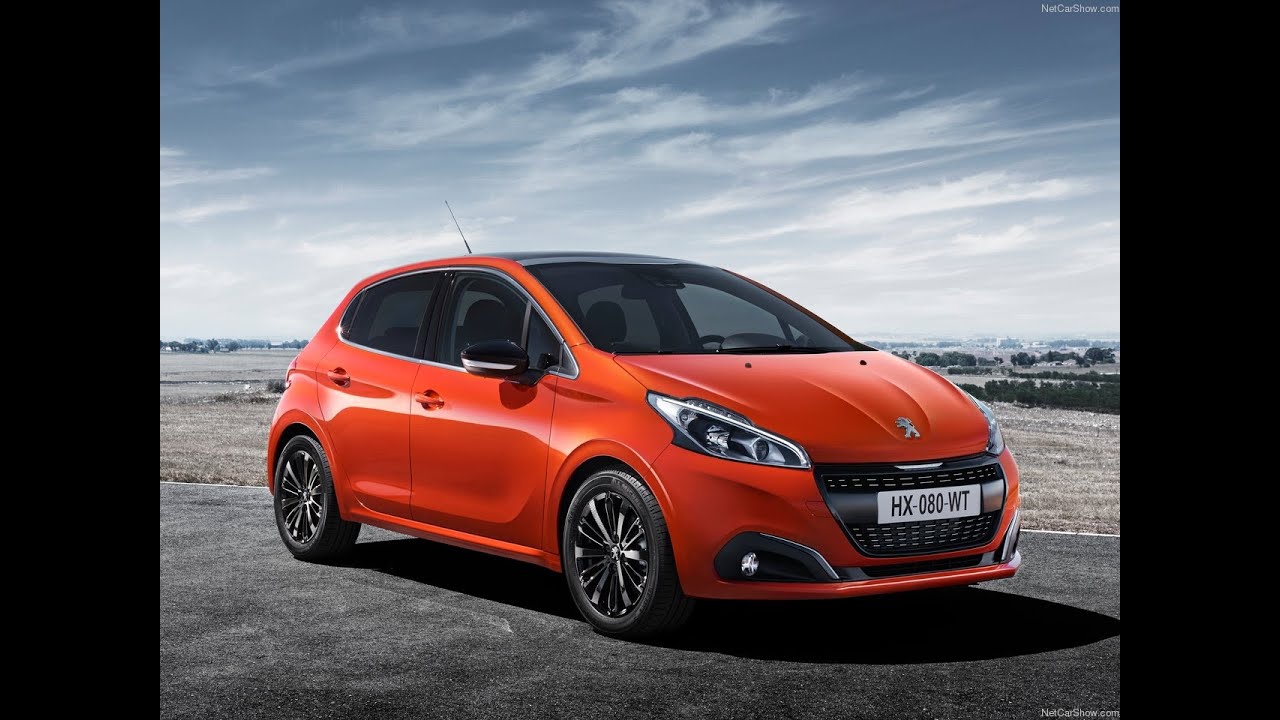
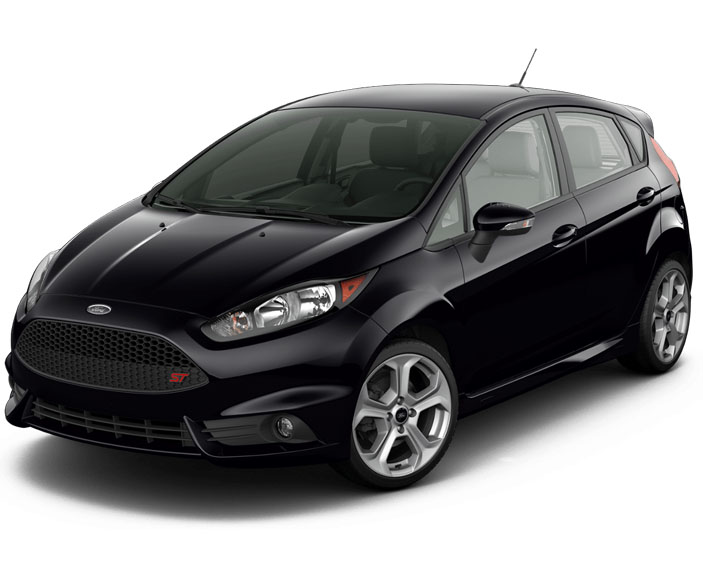
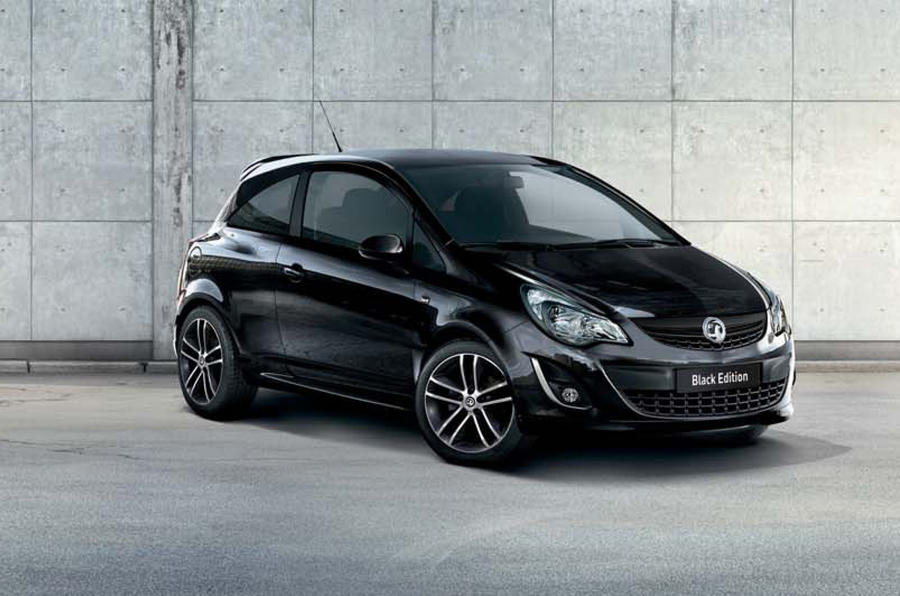
The Volkswagen Golf maintained its position as Europe’s best-selling model in August, with 29,500 units registered, which represented an 11.5% decline on the same period last year. The model maintained its lead despite posting the highest market share drop of any model, moving from 4.3% in August 2015 to 3.5% in August 2016. In contrast, its rival the Opel/Vauxhall Astra was the fourth best-selling model with 14,400 vehicles registered in August 2016, a 23.0% increase on the same period last year. Second in the ranking was the Volkswagen Polo, despite a 10.6% decline; Polo registered just 14,751 units compared to 16,504 for the same period last year. Nonetheless, the Polo was still ahead of the Ford Fiesta even with the model’s significant 11.3% increase in registrations. Amongst the other subcompacts, the Peugeot 208 posted a dramatic 16.5% increase which saw it outperform its rivals the Opel/Vauxhall Corsa and Renault Clio.
In the SUV segment, the Volkswagen Tiguan stood out, registering 14,300 units which is a significant increase of 79.1% which made it the sixth best-selling model in Europe and the best-selling SUV.  The Renault Captur similarly performed well, posting a 19.5% increase which saw it outperform the Nissan Qashqai.
The Audi A4 was the best-selling vehicle in the mid-size range, it entered the top ten ranking with an increase of 44.5% and 12,200 units registered in August 2016.  Other significant segment winners were the Mini Clubman, Honda HR-V, Mercedes GLC, BMW X1, Volkswagen Touran, Hyundai Tuscon, Toyota Prius, Citroen C-Elysee, Ford Ecosport and the Toytoa RAV4.
Felipe Munoz, Global Automotive Analyst at JATO Dynamics commented: “Following the slightly disappointing results in July, August has seen a return to growth. With the Paris Motor Show at the beginning of October, we would expect new launches to further impact the market in Q4 2016.”

Friday, 16 September 2016

European car sales grew by a healthy 9.3% in August led by Italy, Spain and Germany.

  • Italy saw its best August results since 2009, increasing car registrations by 20.2%
  • Spain’s market was boosted by an outstanding growth on rental car registrations, which were up 48%
  • Year-to-date registrations were up 7.6%, with 7.33 million units registered overall so far this year
Registrations in Europe’s ‘Big 5’ markets saw a healthy increase of 9.3% in August, as market conditions improved following the 2% decline seen in July. Overall, registrations for August totalled 562,046 units, up from 514,428 in August 2015. 
Registrations YTD totalled 7.33 million units which is a 7.6% increase on the same period in 2015, SAAR figures came in at 10.92 million units.
While all five markets posted positive growth, Italy was the leader, posting its best August results since 2009 with a 20.2% increase on the same month last year, going from 60,065 units in August 2015 to 72,179 units in the same period this year, in part due to an additional working day.  

The Spanish market grew by 14.3% compared to the same period last year, largely due to record tourist numbers resulting in a 48% increase in rental car registrations. Europe’s largest market, Germany, posted an 8.3% increase, compared to the same period last year. 
This was driven by growth in private registrations which were up 19% on last year due to positive economic development, a healthy level of employment, and two additional working days in August. Both France and the UK posted a modest growth of 6.6% and 3.3% respectively.
Volkswagen Group remained Europe’s largest car maker, posting a 5.8% increase on last year, having registered 143,324 units in August 2016 compared to 135,483 units in August 2015. 
However overall, the German group lost market share, recording the biggest market share drop of all the car makers analysed, going from 26.3% in August 2015 to 25.5% in 2016 as double digit growth in Germany was offset by falls in the UK and France. 
In contrast, Renault-Nissan alliance registrations grew by 12.2%, taking its overall market share to 12.7%, compared to 12.4% last year. 
The group saw strong growth of 27.3% and 32.7% in Italy and the UK respectively, which was particularly boosted by a 33.6% increase posted by Dacia, which outsold Nissan in the ranking. PSA and Ford both lost market share, whilst Opel/Vauxhall dropped by 1% and fell one position in the brand ranking.
The big winner of the month was Daimler, with Mercedes posting double-digit gains in all of the five markets and becoming the third best-selling brand of the month. 
FCA increased its market share by 0.78 percentage points due to the double-digit growth of its Fiat, Jeep, Alfa Romeo and Abarth brands, a 173% increase in sales at Maserati. Hyundai-Kia grew by 21.7%.
“As the market continues to shift and Volkswagen brands continues to slowdown, other brands continue to improve in the mainstream market, such as Dacia, Fiat and Hyundai-Kia which have all seen strong growth, whilst in the premium market, Mercedes is continuing to perform well,” said Felipe Munoz, Global Automotive Analyst at JATO Dynamics.
SUVs continued to boom, accounting for 25.9% of the total market, which is a dramatic increase considering the segment barely outsold subcompact (B-Segment) vehicles in August 2015. 
The SUV segment’s outstanding growth can largely be attributed to midsize and compact SUVs which posted increases of 55.1% and 36.1% respectively. Particularly noteworthy is the new Volkswagen Tiguan, which posted a 74% increase and was the best-selling SUV across the five markets and the fifth best-selling model overall. 
The Tiguan outsold the popular Nissan Qashqai which posted a 2.1% decline, and was significantly ahead of the fast-growing Kia Sportage (+41.3%), Hyundai Tucson (+326.4%) and Renault Kadjar (+79.9%). 
In the B-SUV segment the Opel/Vauxhall Mokka maintained its lead, despite recording a 0% growth, but was closely followed by the Renault Captur which recorded a 9.8% increase compared to the same period last year. 
Other big winners in the segment included the Peugeot 2008, Ford Kuga and Dacia Dusta which posted increases of 40.3%, 52.9% and 34.6% respectively.
The Subcompact segment (B-Segment) was boosted by the Dacia Sandero which increased registrations by 46.4% compared to the same period last year, and was the seventh best-selling model across the five markets in August 2016. 
The Peugeot 208 outsold its popular rivals Renault Clio (down 14.3%) and Volkswagen Polo (down 15.5%) to become the second best-selling subcompact.
The model ranking was again led by the the Volkswagen Golf which remained the best-selling car across the five markets, selling 20,722 units, posting a 5% decline when compared to the same period last year. 
Despite posting a 7.5% increase in Germany, double digit drops across the other markets hindered the model’s performance. 
Despite this, the Golf’s volume was more than double that of the Opel/Vauxhall Astra, which was second in the C-Segment ranking posting a decline of 7.7%. The segment’s big market share winners were the Fiat Tipo, Mini Clubman and Seat Leon.
“While the latest Volkswagen models have helped the brand offset drops posted by their traditional products, other brands gained market share by taking advantage of the booming SUV segment,” concluded Munoz.

Saturday, 3 September 2016

USA SALES AUGUST - HYUNDAI/GENESIS the two brands between them stay stagnant over the over the month.

Riding the wave of hot CUV sales, Hyundai Motor America delivered its best August ever with sales up fractionally over one year ago while the company’s luxury division kicked off sales of its new Genesis G80 mid-luxury sedan.


Hyundai Division posts sales of 70,518 units

“Strong performances by our family of CUVs led us to our best August ever,” said Derrick Hatami, vice president of national sales for Hyundai Motor America. “It’s a similar story to the past couple of months we see continuing as the summer draws to a close.”


Santa Fe (up 69 percent), Santa Fe Sport (up 21 percent), and Tucson (up 15 percent) led the way.

Genesis Division posts sales of 1,497 units

For the first time, the company is reporting sales of the new Genesis luxury brand. As such, sales of the G80 mid-luxury sedan and, shortly, the all-new G90 luxury sedan, will be reported individually. “

It’s exciting to see our first G80s being delivered to customers and we’re very happy with the reception it’s receiving,” said Erwin Raphael, general manager of Genesis in the U.S. market. 

“And I expect we’ll see the first G90s getting to our dealers later this month, another milestone moment for our nascent brand.”


SALES BY BRAND


AUG/2016
AUG/2015
CY/2016
CY/2015
HYUNDAI
70,518
72,012
519,581
514,175
GENESIS
 1,497
0
1,497
0
TOTAL
72,015
72,012
521,078
514,175


MODELS

CARLINE
AUG/2016
AUG/2015
CY/2016
CY/2015
ACCENT
8,329
4,733
54,705
44,985
SONATA
14,888
21,818
139,932
141,556
ELANTRA
20,733
22,405
137,668
173,238
SANTA FE
15,176
11,255
86,948
77,648
AZERA
398
291
3,356
4,358
TUCSON
7,608
6,609
58,000
33,151
VELOSTER
1,986
2,276
16,917
15,537
GENESIS
1,317
2,440
20,818
22,184
EQUUS
83
185
1,237
1,518
G80
1,497
0
1,497
0